🏡
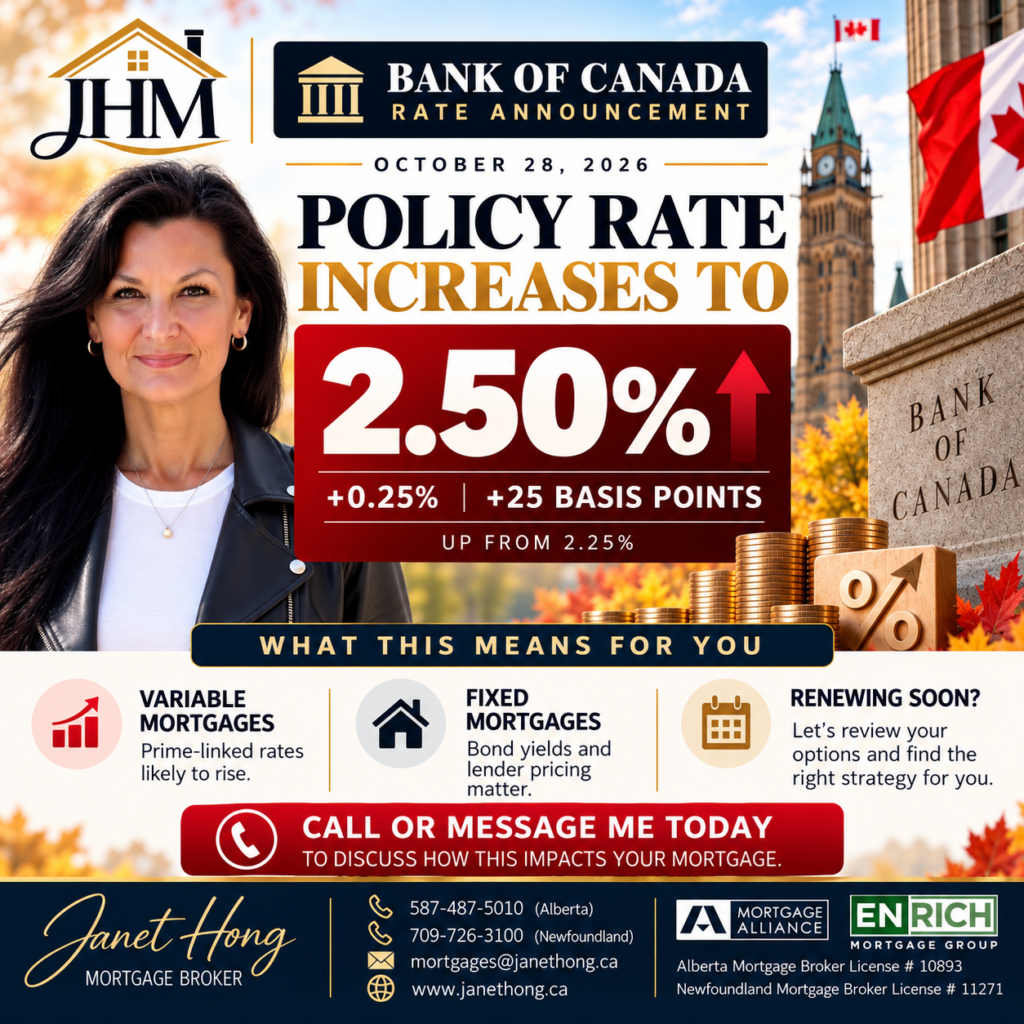
You’ll probably see plenty of posts about the Bank of Canada’s latest rate announcement today. But what does it actually mean for you and your monthly budget?
The truth is, a rate change doesn’t affect everyone the same way. Some homeowners will notice a difference right away, others may feel it gradually, and some won’t see a change until their mortgage renewal.
Let’s break it down with four simple examples. 👇
🏠 1. Mike — The Adjustable Rate Mortgage
Mike has an adjustable rate mortgage, which means his payments change when his mortgage rate changes.
If his rate increases from 3.70% to 3.95%, his monthly payment could rise by around $67, depending on his lender and mortgage details.
That’s more than $800 a year that could be going toward other household expenses.
🏠 2. Jen — The Variable Rate Mortgage With a Fixed Payment
Jen’s payment stays the same, so at first glance, she might think she’s unaffected.
But here’s the catch!
When interest rates rise, more of her payment may go toward interest and less toward paying down her mortgage principal. Depending on her lender’s terms, this can extend her amortization or bring her closer to her trigger rate.
Same payment. Less progress paying down the mortgage.
That’s why it’s so important to understand how your particular mortgage works.
🏠 3. Tom — The Five-Year Fixed Mortgage
Tom locked in a five-year fixed rate, so today’s announcement won’t directly change his current mortgage payment.
But if his renewal is coming up in the next year or two, it’s worth starting the conversation early.
Fixed mortgage rates are influenced by bond market yields and other funding factors, not just the Bank of Canada’s overnight rate.
Planning ahead can help Tom understand his options before renewal day arrives.
🏠 4. Lisa — The Home Equity Line of Credit (HELOC)
Lisa borrowed $150,000 against her home to renovate her kitchen and help with her daughter’s tuition.
Her line of credit has a rate tied to prime, so when her rate increases, her interest costs rise too.
At 4.95%, interest-only payments on $150,000 would be about $619 per month. At 5.20%, they’d be about $650.
That’s roughly $31 more each month — and because she’s making interest-only payments, the balance doesn’t decrease.
This is why it’s important to review not just your mortgage, but your other borrowing as well.
💡 SO, WHO NEEDS TO PAY ATTENTION?
✔️ Adjustable rate mortgage holders may see their payments change.
✔️ Variable rate borrowers with fixed payments should monitor how much of their payment goes toward principal.
✔️ Fixed rate borrowers approaching renewal should start planning ahead.
✔️ Homeowners carrying balances on HELOCs or other prime-linked credit products may see their interest costs increase.
And remember: your lender, mortgage terms and current rate all matter. There isn’t a one-size-fits-all answer.
❤️ HERE’S WHERE I CAN HELP.
If you’re not sure how a rate change affects your mortgage, renewal plans or home equity line of credit, let’s take a look together.
As your mortgage broker, my goal is to help you understand your numbers, explore your options and make informed decisions about your financial future.
No pressure. No confusing jargon. Just straightforward advice tailored to you.
📩 Send me a message. Let’s review your mortgage and make sure you know where you stand.
And if you know someone who could use a little clarity around their mortgage, please share this post!
Sincerely,
Janet Hong, AMPC, CCRMC
Mortgage Broker | Mortgage Alliance & Enrich Mortgages
📍 Alberta Licence: 671095
📍 Newfoundland Licence: 26-08-JH342-1
📱 Text: 709-763-1844 | 587-487-5010
📝 Online Application: https://r.mtg-app.com/hongjanet
📧 mortgages@janethong.ca
🌐 www.janethong.ca
Your home. Your future. Your possibilities. 🏡