Manufactured homes have become an increasingly popular housing option across #Alberta. With traditional home prices remaining out of reach for many buyers, manufactured homes can provide an affordable path to homeownership while still offering privacy, outdoor space, and a detached-home lifestyle.
However, not all manufactured homes are owned the same way.
One of the most important distinctions buyers need to understand is the difference between purchasing a manufactured home located on leased land versus purchasing a manufactured home that sits on land you own.
The ownership structure can significantly impact financing options, monthly costs, future resale value, and long-term wealth building.
What Is a Manufactured Home?
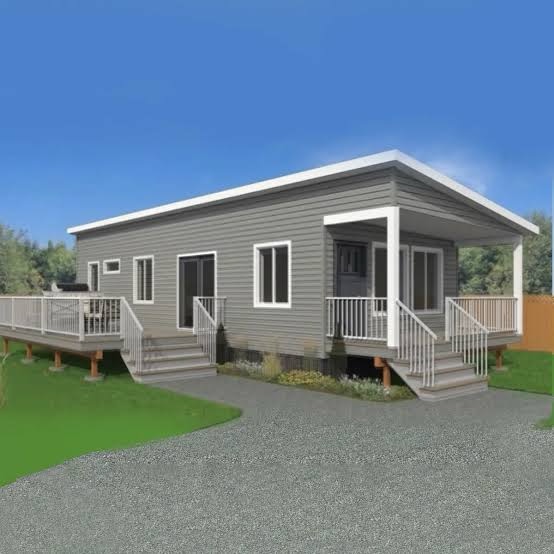
A manufactured home is a factory-built home constructed in a controlled environment and then transported to its permanent location. Modern manufactured homes often include open-concept floor plans, energy-efficient construction, and finishes that rival many site-built homes. There are superb tiny homes and other larger homes that are manufactured, and they can be shipped to you in pieces, or as a complete turn-key home.
Many Albertans are surprised to discover that today’s manufactured homes can be spacious, attractive, and highly affordable compared to traditional detached housing.
Two Types of Manufactured Home Ownership
When purchasing a manufactured home in Alberta, you will generally encounter one of two ownership models:
1. Manufactured Home on Leased Land
In a leased-land community, you own the home itself but do not own the land underneath it. Instead, you lease the lot (often called a “pad” or “site”) from the community owner and pay monthly pad or lot rent.
There are many mobile home parks and manufactured home communities throughout Alberta. It is truly important to do some background research on the landlord who owns the park, to ensure they are not an owner that issues steep increase increases every few periods.
2. Manufactured Home on Owned Land
In this scenario, you purchase both the manufactured home and the land it sits on. Ownership is registered through Alberta’s Land Titles system, just like a traditional house. (Alberta.ca)
This is often referred to as “freehold ownership.”
Manufactured Home on Leased Land
How It Works
When purchasing in a leased-land community:
- You own the home.
- You lease the lot from the park owner.
- You pay monthly pad or lot rent.
- Community rules and regulations apply.
- The relationship between homeowner and landowner is governed by Alberta’s Mobile Home Sites Tenancies Act. (Alberta.ca)
Advantages
Lower Purchase Price
Because you are not purchasing land, the overall cost is often significantly lower than buying a traditional home.
Lower Down Payment Requirement
The purchase price is typically lower, making it easier for buyers to enter the housing market.
Detached Home Lifestyle
Unlike many condos, manufactured homes often provide:
- Private yards
- Driveways
- Outdoor living space
- Greater privacy
Community Amenities
Some communities include:
- Snow removal
- Common area maintenance
- Clubhouses
- Green spaces
Depending on the community, some utilities may also be included in pad rent. (Check with the park before you sign any leases or park prospectus if one exists).
Disadvantages
Monthly Pad Rent
Pad or lot rent is an ongoing expense that continues for as long as you own the home, in the community in which you buy.
Potential Rent Increases
Although Alberta legislation requires significant notice periods before rent increases can occur, pad rents may still increase over time. (Alberta.ca)
Limited Appreciation
Historically, land tends to appreciate more consistently than structures. Since you do not own the land, you may miss out on a significant component of long-term real estate appreciation.
Financing Challenges
Financing can be more difficult because lenders have less security when land is not included.
Many leased-land manufactured homes require:
- Chattel mortgages (a charge over non-real estate, or movable vehicles, farm machinery, or manufactured homes—where the physical item itself serves as security for the debt).
- Specialized financing programs (we do have some lenders that will finance manufactured homes on leased land (Contact me for more info)
- Higher interest rates
- Larger down payments
- Shorter amortization periods
compared to conventional mortgages.
Manufactured Home on Owned Land
How It Works
With freehold ownership, you own:
- The manufactured home
- The land beneath it
- Any improvements on the property
The property is treated similarly to a traditional detached home. (Alberta.ca)
Advantages
Better Financing Options
Most lenders prefer financing properties where both the home and land are included.
Buyers may have access to:
- Conventional mortgage products (available through many of the Big Banks, and numerous other lenders)
- Lower interest rates
- Longer amortizations
- Greater lender choice
Stronger Long-Term Equity Growth
Land historically appreciates over time, making land ownership one of the primary drivers of wealth creation in real estate.
No Pad Rent
Instead of paying monthly site rent, your housing expenses are generally limited to:
- Mortgage payments
- Property taxes
- Utilities
- Maintenance
Greater Control
You are not subject to mobile home park rules, lease agreements, or future pad/lot rent increases (which can be substantial).
Disadvantages
Higher Purchase Price
Because land is included, the initial purchase price is typically higher.
Larger Down Payment
Depending on the lender and property type, buyers may need a larger down payment.
Greater Maintenance Responsibility
You are responsible for all property maintenance, landscaping, repairs, and snow removal.
Financing Differences Buyers Should Understand
As a mortgage broker, one of the biggest distinctions I explain to clients is the financing difference between leased-land and owned-land manufactured homes.
Feature Leased Land Owned Land
Own the Home Yes Yes
Own the Land. No Yes
Monthly Pad Rent Yes No
Traditional Mtg Available Sometimes Usually Yes
Chattel Finance Req’d | Often Rarely
Potential Appreciation | Lower Higher
Equity Growth Poss. Limited Stronger
Lender Options Fewer More
On the whole, manufactured homes placed on owner’s land are easier to finance and may offer better long-term appreciation potential.
Manufactured homes in leased-land communities can still be excellent housing solutions, but I encourage potential buyers to carefully review financing options, pad/lot rent obligations, and community rules and restrictions before purchasing.
Questions Every Buyer Should Ask
Before purchasing a manufactured home, ask:
- Do I own the land or lease the land?
- What is the current monthly pad rent?
- What services are included in the pad rent?
- Are there community rules or age restrictions?
- Has pad rent increased recently? By what percentage? (Some of my leased lot rents increase by 15% annually in Florida, be sure of what you’re getting into before you jump).
- What financing options are available?
- Is the home permanently affixed?
- How old is the home?
- What are the utility costs?
- What is the expected resale market for similar homes?
Final Thoughts
Manufactured homes can be an outstanding affordable housing solution for Albertans. The key is understanding exactly what you’re buying.
If the property includes both the home and the land, you’ll normally enjoy many more financing options and better long-term increase in value potential.
If the property you’re considering is located in a leased-land community, you may benefit from a lower purchase price and lower entry costs, but you’ll need to account for ongoing pad/lot rent and potentially fewer lenders that will finance the home for you.
Before making an offer, I encourage you to closely review the ownership structure, and terms of the leasehold agreement and work with professionals who understand manufactured-home financing. The right guidance can help you avoid surprises and ensure you choose the option that best fits your financial goals.
Need financing for a manufactured home in Alberta?
Whether you’re purchasing in a land-lease community or buying a manufactured home on your own land, I can help you explore your financing options and determine which lenders are the best fit for your situation.
Sincerely,
Janet Hong – Mortgage Broker
Licensed Mortgage Broker – Alberta & Newfoundland
www.janethong.ca | 587-487-5010 | 709-763-1844